
NRIs face one of their most important life decisions when they plan their trip back home - a moment filled with both excitement and apprehension.
More Indians now live abroad than ever before, and an interesting trend has emerged. Many NRIs are moving back to India permanently. This transformation goes beyond just changing locations. It marks the start of a new financial chapter that brings mixed emotions.
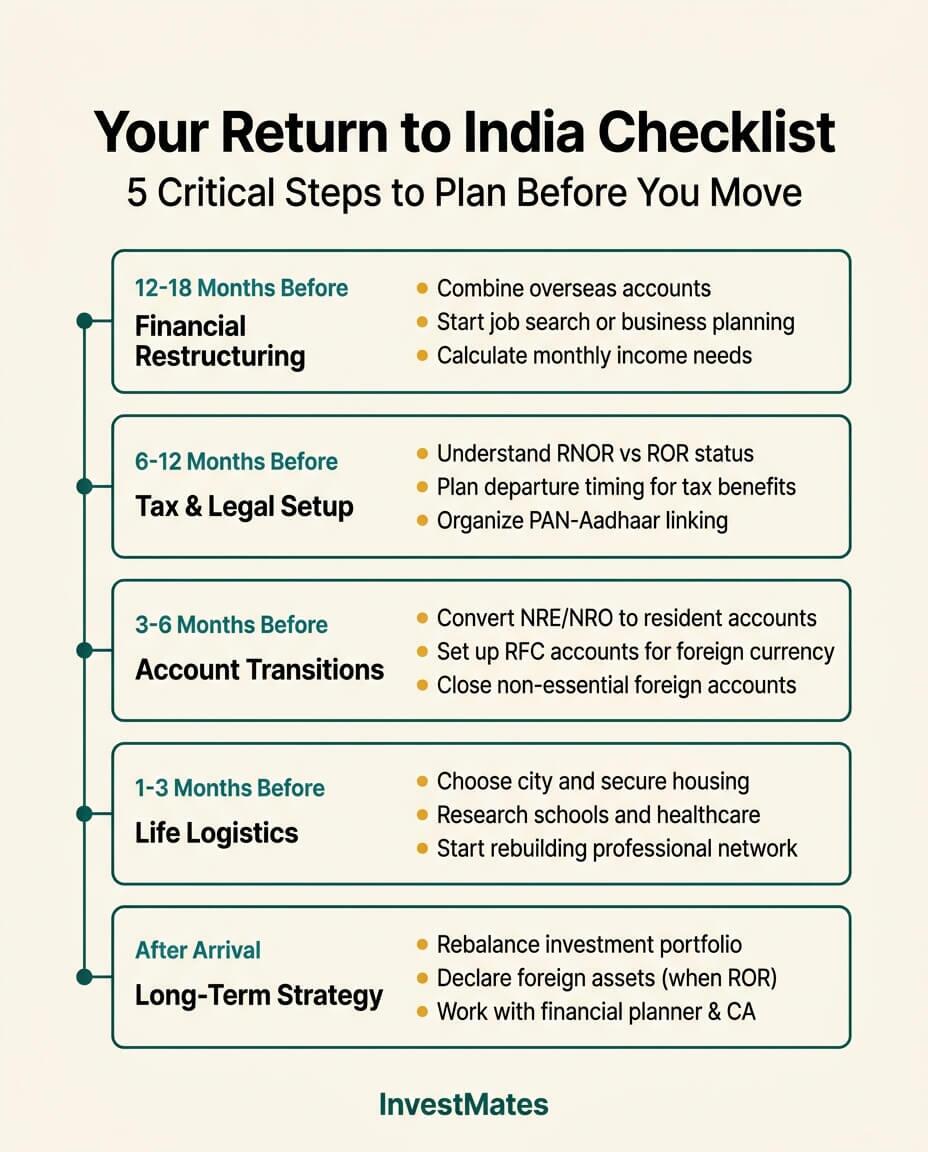
Planning your move back to India works best as a structured project that starts 12 to 18 months before you leave. Each step needs careful planning, from converting overseas accounts to updating investments. You'll need to figure out if your income matches your lifestyle goals.
This piece covers everything you need to know before booking that one-way ticket home. We'll help make your transition smooth and successful.
Assessing Your Readiness to Return
Moving back to India needs careful financial analysis and lifestyle planning. Your preparation will determine whether you have a smooth transition or face unexpected challenges during your experience.
Do you have enough funds to sustain your lifestyle?
Financial planning stands as one of the most complex yet vital parts of returning to India. You should think over how much of your wealth should stay invested abroad versus being moved to India before finalizing your move. A globally diversified portfolio usually reduces overall risk.
You need adequate liquid funds in India to handle immediate expenses like rent, school fees, or healthcare. These liquid funds are the foundations of financial stability during relocation.
Fixed deposit rates in India are set by each bank and change over time, so check your bank's current resident deposit rates before deciding how much cash to hold in deposits and how much to keep invested.
Will you work, retire, or start a business?
Career clarity before moving back is vital, because job uncertainty is a common reason NRIs hesitate to return. Salaries in many Indian industries are lower than in developed countries, though lower living costs and access to household help can narrow the gap.
Start your job hunt 9-12 months before moving and update your CV to match Indian market expectations. At least one family member should have a confirmed job offer to ensure steady monthly income after return.
If you plan to start a business, India has an active startup ecosystem in areas such as fintech, healthtech and consumer businesses. A chartered accountant can help with company setup, GST registration and ongoing regulatory compliance.
It's worth mentioning that planning retirement needs estimates of your living costs, life expectancy, family needs, and provisions for medical emergencies.
How much monthly income will you need?
Your monthly budget depends heavily on your city, housing, schooling, healthcare and family size, so build it from your own expected costs rather than a national average. List fixed costs such as rent or home maintenance, school fees and insurance premiums first, then add living expenses and a buffer for medical emergencies.
Next, map that budget to the income your savings can support. Equity fund withdrawal plans, debt funds, fixed deposits and rental property each carry different levels of risk, return and tax, and returns from market-linked options are not guaranteed. Matching each source to a time horizon, with near-term needs in lower-risk options, helps keep your income steady.
Simplifying Your Finances Before the Move
Financial streamlining is a vital step in your repatriation experience. You should take care of money matters well ahead to avoid complications after settling back in India.
Combine bank accounts and investments
The first step is to review all your financial accounts in different countries. Most NRIs have multiple accounts that should be combined before returning. You should liquidate non-essential assets and bring scattered investments together to make management easier.
Your NRE and NRO accounts must change status once you return to India to live. RBI rules require NRE accounts to be redesignated as resident accounts, or their funds moved to a Resident Foreign Currency (RFC) account, immediately on your return, and NRO accounts are redesignated as resident accounts. Interest on an NRE account is tax-free only while you are a person resident outside India under FEMA, so that exemption ends when you move back, even if you are RNOR for income tax. Our guide on what happens if you delay converting your NRE account covers the timing and penalty questions.
RFC accounts let you keep foreign currency without converting it to Indian rupees right away. FCNR deposits can continue until maturity at the contracted rate if you wish, and on maturity the money moves to a resident rupee account or an RFC account.
For the full step-by-step sequence - including FEMA timelines and the documents each bank asks for - see our complete repatriation checklist.
Exit planning from host country
Smart timing of your departure can help you save on taxes. Your return date should match tax residency rules in both countries. A few extra months of stay might lead to substantial tax savings.
Your host country might need exit tax returns or final declarations. Make sure to document your departure date, change of domicile, and tax payments in your previous home to prevent legal issues in either country.
If you are leaving the US, the year you move is usually a dual-status year, with a US resident period and a nonresident period. A green card holder stays a US tax resident until that status is formally ended, for example by filing Form I-407 with USCIS to abandon it. US citizens who renounce, and long-term residents who end their residency, must also file Form 8854 and may owe the expatriation tax if they are covered expatriates. See our guide on filing US and India taxes in the year you move back for the return-year forms.
While you are a US tax resident, you generally must report Indian bank accounts, including NRE, NRO and FCNR accounts, on the FBAR (FinCEN Form 114) when your foreign accounts together exceed $10,000 at any time in the year. Specified foreign assets such as Indian mutual funds and shares are reported on Form 8938 under FATCA once they cross that form's thresholds.
Organize the core team documents: PAN, Aadhaar, OCI
Once you decide to return, update the address and contact details linked to your PAN and in your income tax e-filing profile. Once you are a resident and have an Aadhaar number, link it with your PAN: the non-resident exemption from linking no longer applies, and an unlinked PAN can become inoperative.
If you do not already have Aadhaar, check the current Aadhaar enrolment rules for NRIs and the accepted identity and address documents on the UIDAI website, then book an appointment or visit your nearest Aadhaar Seva Kendra.
Yes, it is crucial to organize your family's documents too. Make sure everyone has current passports, Aadhaar cards (if eligible), and PAN cards. This preparation makes everything easier when you return to India, from banking to property deals.
Tax and Legal Compliance for Returning NRIs
Your tax implications in India depend on your residential status. These details will help you manage your finances better in your first years after moving back.
Understanding RNOR and ROR status
When you return to India, your residency status moves through stages - NRI, then usually RNOR (Resident but Not Ordinarily Resident), then full resident (ROR).
During your RNOR years, income that accrues or arises outside India is generally not taxed in India, unless it comes from a business controlled in India or a profession set up in India. Once you're a full resident (ROR), your worldwide income becomes taxable.
You qualify as RNOR in a year if you were a non-resident in 9 of the previous 10 years, or spent 729 days or less in India in the previous 7 years, so exactly how many RNOR years you get depends on your move-back date.
See our full RNOR window guide for the exact mechanics and a calculator, and our tax planning guide for returning NRIs for how to use those years.
Foreign asset disclosure requirements
As an RNOR, you don't need to declare foreign assets in your income tax returns. This gives you time to settle back comfortably.
In spite of that, you must report all foreign assets in Schedule FA of your tax returns when you become an ROR. This covers:
- Foreign bank accounts
- Overseas property
- Investments in foreign stocks/securities
- Other international assets
The Black Money Act imposes heavy penalties if you fail to disclose these assets. Accurate records of your global financial holdings are crucial for future compliance.
Double Taxation Avoidance Agreement (DTAA)
India has comprehensive DTAAs with many countries, including the US and the UK, to prevent double taxation of income. These agreements give you three main benefits:
- Foreign Tax Credit for taxes paid overseas
- Exemptions for certain income categories
- Reduced tax rates on specific income types
To claim DTAA benefits as a credit in India for tax paid abroad, file the prescribed statement with proof of the foreign tax paid: Form 67 for tax years up to 2025-26, and Form 44, which replaces it under the Income-tax Rules, 2026, for later years.
Note that DTAA benefits continue through your RNOR period but become vital once you're an ROR and your global income falls under India's tax net.
Rebuilding Your Life in India
Finding a comfortable place to live is one of the most important steps when you return to India permanently. Your daily life quality depends on where and how you settle back, beyond just managing your finances.
Choosing the right city and home
The place you pick will shape your entire return experience. Bengaluru, Hyderabad, Pune, and Chennai are popular with returning NRIs for their job markets, infrastructure, and lifestyle options, while Mumbai and Delhi draw many people despite higher living costs. Healthcare access, schools and commute times are worth weighing alongside jobs.
Living costs, especially rent, differ substantially between cities and even between neighbourhoods in the same city. Compare current rental listings in the areas you are considering, and if possible rent for your first year before buying a home.
Schooling and healthcare access
Parents need to think about good schools for their children. Bengaluru, Pune, and Chennai stand out with their international schools and universities that match global education standards.
Private healthcare costs in India vary widely by hospital and city. Arrange Indian health insurance before or soon after you arrive, and check which hospitals near your new home are in your insurer's network.
Rebuilding your social and professional network
A good support system makes settling back easier. Start by reaching out to old college friends, former colleagues, and neighbors who can help you adjust. LinkedIn and other professional platforms are great ways to showcase your international background.
Digital connections help, but meeting people in person works best in India. You should join industry events, connect with alumni groups, and try co-working spaces like WeWork or 91springboard. These places host workshops and meetups that help you network naturally. Remember that moving back isn't just about changing locations - it's about reinventing yourself and finding your new definition of home.
Creating a Long-Term Financial Strategy
A resilient financial framework needs careful planning after you settle back in India. Your overseas earnings and investments require careful restructuring to maximize returns in your home country.
Rebalancing your investment portfolio
Portfolio assessment becomes significant after settling in India. You need a combined real-time dashboard that shows your exact allocation across asset classes. The step-by-step rebalancing process helps you identify over-performing assets to trim and under-performing ones to increase.
Fresh investments can be redirected toward under-allocated areas instead of selling appreciated assets directly. For transfers on or after 23 July 2024, long-term gains on listed equity shares and equity-oriented fund units held for more than 12 months are taxed at 12.5% on the amount above ₹1.25 lakh a year.
Using RFC accounts and tax-free options
Resident Foreign Currency (RFC) accounts are excellent tools for returning NRIs. These accounts help you hold foreign currency earnings without immediate conversion to rupees. The account can be held in any freely convertible foreign currency, and RBI allows the balance to be used freely for bona fide remittances outside India, including investments abroad.
The tax benefits are substantial. Interest earned on RFC accounts stays exempt from Indian income tax during your RNOR period. You'll need to pay tax on interest earned as per your tax slab after this period.
Working with a financial planner and CA
Professional guidance is a great way to get through your transition. A specialized team should include a financial planner for portfolio structure and a chartered accountant who knows NRI taxation well.
Expert professionals help with property transactions, repatriation services, and tax litigation. They monitor investments, make liquidation of property easier, and advise on repatriation of sale proceeds. A focused tax plan customized to your situation can substantially affect your financial success.
Conclusion
Moving back to India after years abroad is a major life change that needs careful planning on several fronts. Your success in returning home largely depends on how well you prepare financially, legally, and emotionally before the big move.
Money management is the life-blood of your return experience. You should start preparing 12-18 months before your planned return date. This gives you time to unite your accounts, understand tax implications, and build cash reserves. The RNOR status gives you tax advantages in your first few years back, so timing your return well can help you make the most of these benefits.
Your paperwork needs equal attention. Update your PAN details before you fly, link Aadhaar with your PAN once you have it, and remember that foreign assets must be disclosed in Schedule FA once you become a resident and ordinarily resident (ROR). The city you choose will also affect your quality of life substantially. Each metro area has its own advantages in terms of living costs, healthcare access, and job opportunities.
Expert guidance can make a real difference during this transition. Working with financial planners and chartered accountants who know NRI taxation helps you direct complex financial matters and avoid common mistakes. RFC accounts are great options to keep your foreign currency earnings without converting them to rupees right away.
Note that coming home involves more than just logistics - you need to adjust emotionally too. Building new social and professional networks takes time and effort. Many returning NRIs find this rewarding as they use their global experience to help India grow.
Your return marks a fresh start, not an end. With proper planning, smart financial management, and realistic expectations about lifestyle changes, you can turn challenges into opportunities as you start this new chapter of life in India.
Frequently asked questions
What financial steps should NRIs take before returning to India?
NRIs should consolidate bank accounts and investments, convert NRE/NRO accounts to resident accounts, and consider opening a Resident Foreign Currency (RFC) account. It's also important to organize key documents like PAN and Aadhaar, and plan for tax implications.
How does the tax status change for NRIs returning to India?
Upon return, many NRIs qualify as Resident but Not Ordinarily Resident (RNOR) for their first few tax years, depending on how many of the previous 10 years they were non-resident and how many days they spent in India in the previous 7 years. As an RNOR, income that accrues or arises outside India is generally not taxed in India unless it comes from a business controlled in or a profession set up in India. After you become Resident and Ordinarily Resident (ROR), your global income becomes taxable in India.
What factors should NRIs consider when choosing a city to settle in India?
NRIs should consider job markets, infrastructure, healthcare facilities, education options, and cost of living. Cities like Bengaluru, Hyderabad, Pune, and Chennai are popular choices due to their balance of these factors.
What role do financial professionals play in an NRI's return to India?
Financial planners and chartered accountants familiar with NRI taxation can provide crucial guidance on portfolio restructuring, tax planning, property transactions, and repatriation services. Their expertise can significantly impact financial success during the transition.